Base Oil Market News Update
Returning Base Oil Cargoes to Nigeria and Asian Export Shifts: What Mid-October 2026 Means for Buyers
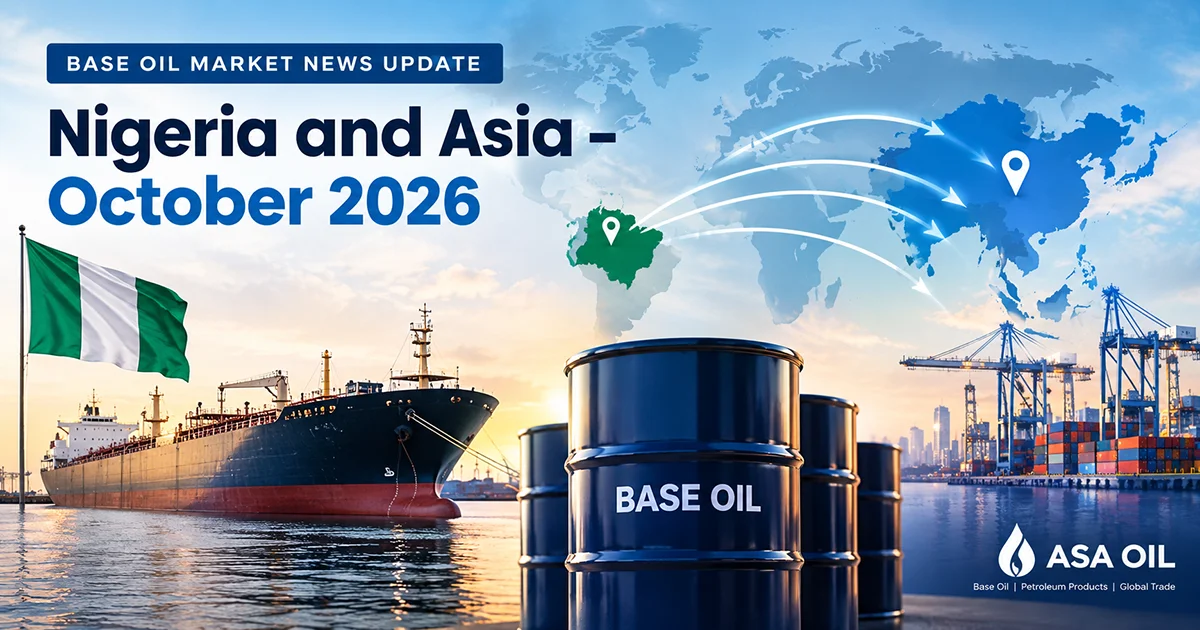
In the week to 16 October 2026, specialist market reporting showed cargoes of base oil moving again from southern Europe and Greece toward Nigeria, with an additional US Gulf cargo expected to load around mid-October for later delivery.
At the same time, Asian supply patterns shifted: Taiwan shipments slowed ahead of maintenance, Singapore retained more material regionally, and South Korea’s September exports redirected toward India. These developments matter for lubricant blenders and importers in West Africa and India because they affect the near-term availability of specific base oil groups rather than creating a uniform surplus.
The latest Base Oil Market News for October 2026 highlights changing cargo flows, shifting export patterns in Asia, and renewed shipments toward Nigeria. These developments are important for international buyers monitoring base oil availability, regional demand, and procurement opportunities.
Executive Summary
- European and expected US cargoes to Nigeria in mid-October signal a modest return of spare Atlantic supply after earlier tightness.
- South Korea’s September base oil exports fell to a four-month low of 339,000 tones, with sharp declines to China offset by higher flows to India.
- Taiwan’s export slowdown, linked to mid-October maintenance, and Singapore’s regional retention reshape Asian availability.
- Buyers should distinguish Group I and Group II grades; heavy Group I availability has improved in India while lighter or premium grades remain more constrained in places.
- Lead times, grade match, and documentation remain critical even when directional supply improves.
What the Mid-October Cargo Data Shows
Base Oil News reported that a cargo loaded from southern Europe in the past week headed to Nigeria, with delivery due in late October, and a Group I cargo from Greece loaded in early October was also end route with similar timing. An additional cargo was expected to load from the US Gulf around mid-October for Nigeria.
Parallel movements included a Northwest European cargo toward South Africa (delivery first-half November) and earlier US Gulf material arriving in South Africa with possible onward movement.
These flows coincide with the arrival of earlier Asian cargoes in the Americas, reducing the immediate need for Atlantic barrels to move east. The result is a small but observable reappearance of spare supply in the Atlantic Basin. For Nigerian buyers, who have historically relied on a mix of term and spot volumes, the return of European Group I and expected US material offers an incremental alternative to previously tighter conditions.
Asian Export Reshuffling and Maintenance
Asia’s picture is one of redistribution rather than net loss. Taiwan’s shipments slowed for a third week ahead of plant maintenance expected to start around mid-October. Formosa Petrochemical’s Mailiao refinery was also reported to be reducing crude runs in October and November for maintenance, providing broader refining context.
A large Taiwan Group II cargo (light and heavy grades) loaded in the second half of September was due to arrive in India around the end of the week of 16 October.
South Korea’s September exports totaled 339,000 tonnes, down from more than 361,000 tonnes in August and 12 percent lower year-on-year — the first annual decline in four months and a four-month low. Shipments to China fell to just over 12,000 tonnes (versus an average of about 44,000 tonnes per month earlier in the year), while Southeast Asia received 64,500 tonnes.
In contrast, exports to India rose to more than 96,000 tonnes, the highest in six months. Higher Chinese Group III availability and recovering Singapore domestic supply reduced the competitiveness of some South Korean barrels in those markets, redirecting volumes toward firmer Indian demand.
Singapore, meanwhile, was reported to be keeping more of its supply within Asia. These shifts mean that the region’s export cushion for distant markets is tighter in places even as overall Atlantic spare supply improves.
India and Africa Context
India continues to draw Asian material. In addition to the Taiwan Group II arrival, South Korean September flows to India were elevated. Separate reporting indicated that India’s Group I heavy-grade (Base Oil SN500 and bright stock) import prices softened in October on rising supply availability from Asia (post-maintenance China and Thailand volumes) and diversions from the US and Europe.
Lighter Base Oil SN150 supply remained more limited. Blenders had largely stocked ahead of expected Saudi maintenance later in the fourth quarter.
In Africa, the Nigerian cargoes represent a notable change from earlier periods when spot shipments were scarce. South Africa also received European and US material. These movements do not imply uniform abundance across all African markets or all grades; Nigeria’s import needs and local blending activity differ from those of South Africa, Kenya, or Egypt. Port access, foreign-exchange conditions, and packaging preferences further differentiate landed economics.

Technical Distinctions That Matter to Buyers
Base oils are not interchangeable. API Group I material (typically solvent-refined, higher sulfur and aromatics) differs in viscosity index, saturates, and performance from Group II (hydro processed) and Group III (higher-VI hydro processed or GTL-type).
The European cargoes highlighted in the mid-October data included Group I; the Taiwan material included Group II light and heavy grades. A buyer seeking bright stock or a specific viscosity (for example, SN500 versus N150) must verify the exact grade, kinematic viscosity at 40 °C and 100 °C, viscosity index, pour point, and sulfur content against formulation requirements.
Virgin base oils produced from refinery streams also differ from re-refined material in consistency and, in some cases, regulatory acceptance for certain finished lubricants. Re-refined adoption has increased in Europe amid earlier Middle East constraints, but suitability remains application-specific. Finished lubricants contain additives; the base oil is the primary stock, not the finished product.
Base Oil Market News: Implications for Global Buyers
Following Base Oil Market News helps importers identify changes in supply availability, regional demand, and export opportunities. The October 2026 developments in Nigeria, India, and Asia highlight why buyers should evaluate individual grades, shipping schedules, and supplier offers instead of relying solely on broad market trends.
Industry and Buyer Implications
For Nigerian and broader West African importers, the return of European Group I and expected US cargoes may ease near-term spot availability for certain grades. However, volumes appear modest relative to historical peaks, and confirmation of discharge and local distribution will determine practical impact.
Indian buyers continue to benefit from redirected Asian premium-grade flows, while heavy Group I have become more available. Southeast Asian and Chinese buyers face tighter South Korean and Taiwanese options in the short term.
Procurement teams should focus on:
- Exact API group, viscosity grade, and full specification match.
- Origin documentation, quality inspection (SGS or equivalent), and certificate of analysis.
- Packaging (bulk versus drums or IBCs) and contamination controls during ocean transport.
- Lead time versus inventory position, especially ahead of further fourth-quarter maintenance.
- Landed-cost components: freight, insurance, duties, and port handling, which vary significantly between West African and Indian destinations.
Weak base-oil margins relative to diesel continue to influence refinery output decisions, so any improvement in availability can reverse if refiners maximize fuel production.
Base Oil Supply Trends in October 2026
Global Base Oil Supply Trends in October 2026 reflect changing cargo flows, regional export patterns, and differences in demand across major markets. Renewed shipments toward Nigeria, lower September export volumes from South Korea, and evolving supply conditions in India highlight the importance of monitoring regional developments.
For international buyers, understanding Base Oil Supply Trends can help with sourcing decisions, comparing supplier offers, selecting suitable base oil grades, and planning shipments more effectively. Importers should verify current availability, product specifications, and delivery schedules with their suppliers before placing orders.
Base Oil Market News: Key Takeaways for Buyers
For buyers following Base Oil Market News, the key consideration is whether changes in export volumes translate into actual availability of the required grades. Importers should compare supplier quotations, verify technical specifications, and review shipping schedules before making purchasing decisions.
Regional developments in Nigeria, India, and Southeast Asia may affect sourcing options differently depending on the base oil group and viscosity grade.
Base Oil Market Update
Monitor subsequent weekly cargo-flow updates for confirmation that the expected US cargo to Nigeria loads and that European material clears. Track Taiwan and any Saudi maintenance progress and their effect on October–November export volumes.
Watch South Korean and Singapore export statistics for October to see whether the India redirection and regional retention persist. Indian buyers may also watch domestic Group I plant activity and the seasonal demand shift toward lighter grades.
Frequently Asked Questions
Does the return of cargoes to Nigeria mean base oil is now abundant in West Africa?
No. The mid-October movements indicate a modest reappearance of spare Atlantic supply after earlier tightness. Actual availability still depends on grade, volume, and local demand. Spot buyers should verify specific offers rather than assume broad surplus.
Why did South Korean exports to China fall while flows to India rose?
Higher Group III availability and lower prices in China reduced the competitiveness of some South Korean barrels there. Firmer Indian demand and pricing attracted more volume, with September shipments to India exceeding 96,000 tonnes.
Are Group I and Group II base oils interchangeable in lubricant formulations?
Not automatically. They differ in saturates, sulfur, viscosity index, and oxidation stability. Formulation adjustments or additive packages are often required when switching groups. Always match the specification to the intended application.
How does Taiwan maintenance affect regional supply?
The slowdown in Taiwan shipments ahead of mid-October maintenance, combined with broader Mailiao run cuts, reduces short-term export availability from that source. Singapore and other producers may partially offset, but regional buyers can face tighter options for certain grades.
What documentation should importers request for base oil cargoes?
Typical requirements include a certificate of analysis covering key parameters (viscosity, VI, pour point, flash point, sulfur), quality inspection certificate, bill of lading, and origin documents. Confirm that the material meets the contractual specification before shipment.
Choosing a Reliable Base Oil Supplier
As global base oil trade flows continue to shift, choosing a reliable Base Oil Supplier is essential for buyers seeking consistent product quality, competitive pricing, and dependable delivery schedules.
Importers in Nigeria, India, and other Asian and African markets should evaluate product specifications, available grades, packaging options, and export logistics before placing an order. Working with an experienced supplier such as ASA Oil can help buyers source suitable base oil products and manage international procurement more efficiently.
Conclusion
This October 2026 Base Oil Market News update highlights a changing global market, with Atlantic cargoes returning to Nigeria while Asian export flows continue to shift in response to maintenance and regional demand.
For international buyers, the practical takeaway is grade-specific rather than directional alone. Verifying specifications, monitoring subsequent cargo updates, and aligning procurement with actual formulation needs remain more useful than assuming broad tightness or surplus.
Readers seeking to discuss base oil requirements can explore product options and request technical details through ASA Oil’s contact channels.